The Order You Can’t Afford to Take
By Anthony Collin, CEO of Smart Business Funding
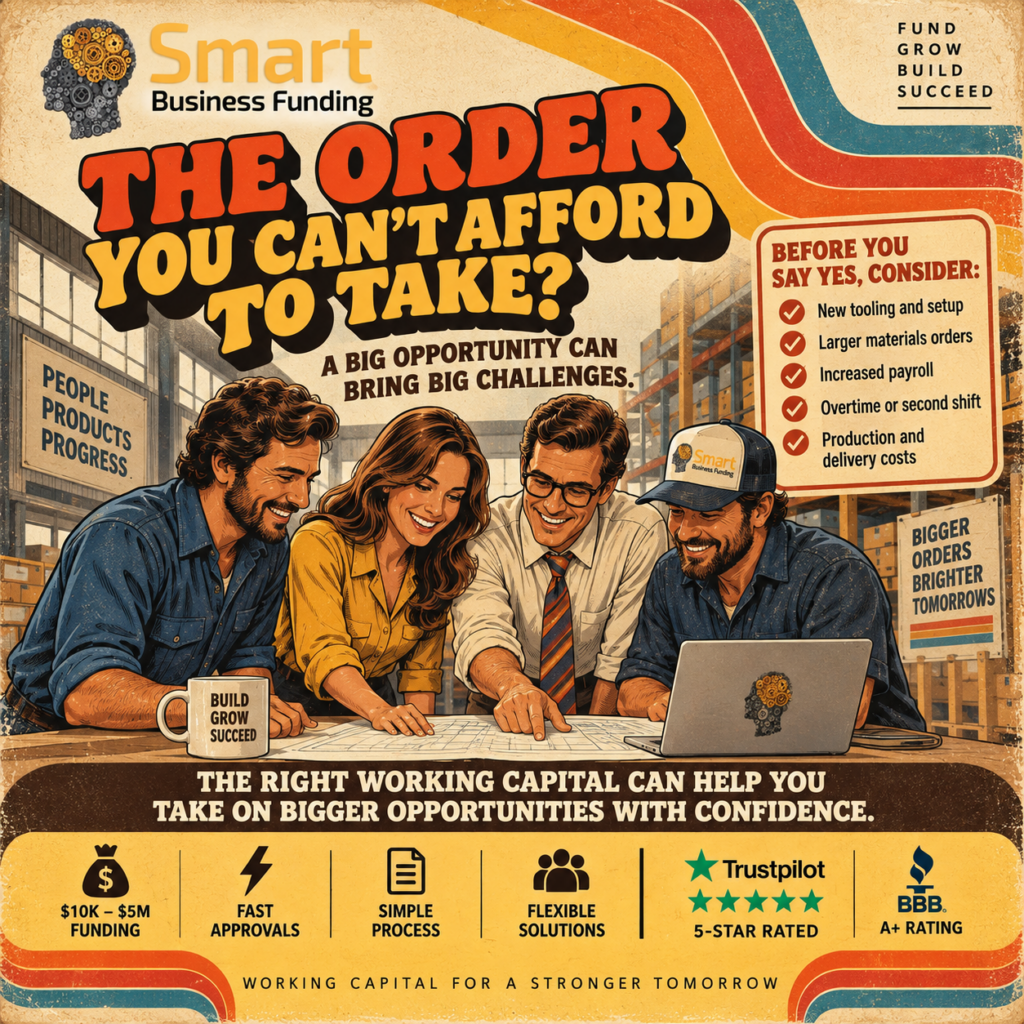
A new client sends over a purchase order that’s larger than anything you’ve run before. It’s the kind of contract that could change the trajectory of the business — except taking it means new tooling has to be built, a much larger materials order has to go out, and you’ll likely need a second shift to hit the delivery date. All of that has to happen before a single dollar of the contract itself comes in.
I’ve watched this exact moment play out with manufacturing and production business owners for over a decade, and it’s one of the strangest problems in the industry: the contract that should be a business’s best quarter can instead become its most dangerous one, purely because of timing. The work is real. The client is real. The only thing standing between the business and a genuine growth milestone is the cash to get from “we won the bid” to “we shipped the first order.”
This guide walks through why this happens, what it actually costs to solve badly, and how to think about funding the gap the right way.
Why This Trap Catches Growing Businesses, Not Struggling Ones
It’s worth naming the pattern directly: this isn’t a sign of a business in trouble. It’s almost the opposite. The businesses that hit this wall are usually the ones executing well enough to win larger contracts than their current cash position was built around. A shop sized for $200,000 orders that wins a $600,000 contract isn’t undercapitalized because of mismanagement — it’s undercapitalized because it just grew faster than its balance sheet.
That distinction matters, because it changes how the funding decision should be framed. This isn’t “we need help to survive.” It’s “we need to bridge a gap that only exists because we’re about to be a bigger business than we were yesterday.”
What Taking the Order Actually Requires — Before It Pays
1. Tooling and Setup Costs
Many contracts, especially first orders from a new client, require dedicated tooling, dies, molds, or fixtures specific to their part. That cost is typically due upfront to the tooling vendor, often weeks or months before the first production run even starts — and long before the client’s invoice terms would release any cash back to you.
2. A Much Larger Materials Order
A bigger contract usually means a bigger raw materials commitment than your normal purchasing pattern. Suppliers extend credit based on your history with them, not the new contract you just won, so a large first materials buy for a new job often has to be paid closer to the point of delivery — cash out the door well before the finished goods ship, let alone before the client pays.
3. A Second Shift or Overtime Labor
Hitting a new delivery timeline frequently means adding a second shift, bringing on temporary labor, or authorizing significant overtime — all of which hit payroll on your normal cycle, regardless of when the client’s invoice is due. Labor is one of the least flexible costs in this equation: it has to be paid on time even though the revenue it’s producing hasn’t arrived yet.
4. The Cost of Getting This Wrong
If the cash isn’t there to cover tooling, materials, and labor cleanly, the alternatives are all expensive in their own way: delaying the start date and risking the relationship with a new client, under-ordering materials and risking a missed delivery, or stretching existing vendor payments to free up cash — which strains the supplier relationships you’ll need for the next big contract too. None of these are catastrophic on their own, but each one quietly reduces the odds that this contract turns into a repeat relationship rather than a one-time scramble.
A Practical Framework for Sizing the Gap Before You Say Yes
Before committing to a contract that stretches your current capacity, it helps to map the timeline explicitly:
- List every upfront cost — tooling, the initial materials order, and any additional labor — with a rough dollar figure and a due date for each.
- Map the client’s payment terms — when does the first invoice go out, and how many days until it’s actually expected to clear?
- Identify the gap window — the number of days (and dollars) between when your costs are due and when the client’s payment is expected.
- Compare that gap against your current cash position — can the business absorb it from existing reserves, or does it require external funding to avoid disrupting normal operations?
Running this exercise before accepting the contract — not after tooling is already ordered — is what turns a stressful scramble into a manageable, planned decision.
Growth Capital as the Right Frame, Not a Bailout
It’s worth being direct about the framing here, because it changes the conversation both internally and with a lender: this is growth capital, not distress capital. The business isn’t funding a shortfall caused by declining sales — it’s funding the on-ramp to a larger order book than it had before. Lenders and funding partners evaluate that very differently than they evaluate a business trying to stay afloat, and it’s a distinction worth being clear-eyed about when you’re deciding how to move forward.
How the Direct Fund Program Fits
Smart Business Funding’s Direct Fund Program is built to cover exactly this kind of upfront gap. Manufacturing and production businesses can access funding from $10,000 to $5,000,000, with underwriting typically completed in one to five hours and funding available as fast as the same or next business day — timing that matters when a tooling vendor or materials supplier needs payment well before a new client’s invoice is due.
Repayment is structured as a fixed daily or weekly remittance based on the business’s overall revenue and operations — not paused or tied to when the specific new contract’s invoice clears. That’s an important distinction: the funding covers the gap, but repayment runs on its own fixed schedule regardless of that particular client’s payment timeline, so it’s worth planning cash flow with that in mind rather than assuming repayment and the new contract’s payout are linked. Full program details are available on the Merchant Cash Advance page.
Businesses with at least one year in operation, $50,000 or more in monthly revenue, and a credit score around 500 or higher (soft pull only, so checking eligibility doesn’t affect your credit) can typically get a straightforward answer on qualification.
If the growth is less about a single contract and more about a broader expansion — a new production line, added floor space, or a permanent second shift — it’s worth reviewing growth and expansion capital more broadly rather than funding tied to one order. And if new or upgraded machinery is part of what’s needed to fulfill the contract, equipment financing is a separate option worth comparing against working capital for the tooling and materials side of the gap.
This Pattern Shows Up Across Manufacturing and Production Sectors
Contract manufacturers scaling to serve a new OEM relationship, metal and plastics fabricators winning a larger construction or infrastructure bid, and packaging producers landing a first order from a major retail or CPG client all tend to hit this exact wall — a contract sized beyond their current working capital cycle. You can review how funding applies to your specific sector on the Industries page.
Why Manufacturers Work With Smart Business Funding
Smart Business Funding (Collins Cash Inc. d/b/a Smart Business Funding) has funded businesses across all 50 states since December 2014 and holds an A+ rating with the Better Business Bureau, a five-star average on Trustpilot, and was named to the Inc. 5000 list of fastest-growing private companies in 2020. The company has funded more than $500 million to businesses nationwide, including manufacturers scaling into contracts larger than their existing working capital was built to support.
Ready to Take the Order Without the Cash Crunch?
If a new contract requires tooling, materials, or labor costs before a single invoice clears, apply now to see what you qualify for — with no impact to your credit to check.
Want to talk through how funding could line up with a specific contract’s timeline? Contact us or call 1-866-Re-Smart to walk through it with our team.
Frequently Asked Questions
Is needing funding to take a big new contract a bad sign for my business? No — it’s a common gap for growing manufacturers whose new order size has outpaced their current working capital cycle. It reflects growth outrunning cash flow, not financial distress.
What costs typically come up before a new contract pays out? Tooling and setup costs, a larger-than-usual materials order, and additional labor from a second shift or overtime are the most common upfront costs, all of which are typically due well before a new client’s invoice terms release any cash.
Is repayment tied to when the new contract’s invoice gets paid? No. Repayment on the Direct Fund Program runs as a fixed daily or weekly remittance based on the business’s overall operations, on its own schedule — it isn’t paused or tied specifically to when any one contract’s invoice clears.
How quickly can a manufacturer get funded to prepare for a new contract? Underwriting typically takes one to five hours, with funding available same-day or next-day in many cases — timing built around the kind of upfront costs a new contract requires.
Should I fund the tooling and materials separately from any new equipment I need? Often, yes. Working capital through the Direct Fund Program is suited to tooling, materials, and labor costs, while equipment financing is structured specifically around acquiring or upgrading machinery — the two can be evaluated separately depending on what the new contract actually requires.
About the Author
Anthony Collin is the CEO of Smart Business Funding (Collins Cash Inc.), a direct funding provider that has worked with manufacturing, production, and small business owners across all 50 states since December 2014. Smart Business Funding holds an A+ Better Business Bureau rating and a five-star Trustpilot average, and was named to the Inc. 5000 in 2020.