The Hidden Cost of Waiting on Net-60 Payment Terms
By Anthony Collin, CEO of Smart Business Funding
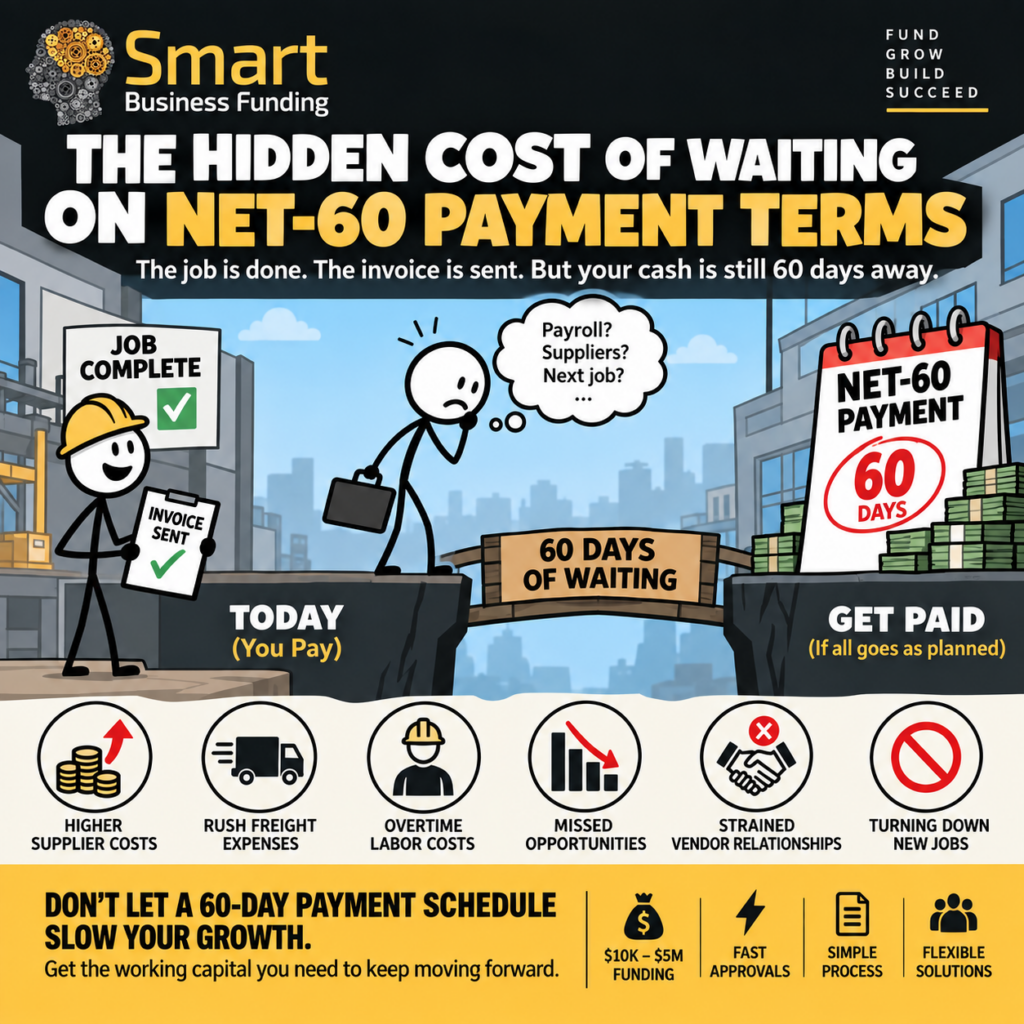
A customer signs off on a production run. The materials are ordered, the line is scheduled, payroll goes out to run it, and the finished product ships on time. By every operational measure, the job is done well. Then the invoice goes out — net-60 — and the cash for work you already completed doesn’t show up for two more months.
I’ve worked with manufacturing and production business owners across the country for over a decade, and this is one of the most common — and most misunderstood — cash flow problems in the industry. It isn’t a sign the business is struggling. It’s a structural gap built into how larger clients pay, and it hits healthy, growing shops just as hard as anyone else. In some cases, it hits growing shops harder, because more orders mean more cash sitting in that 30-to-90-day gap at any given time.
This guide breaks down what that waiting period actually costs — beyond the obvious — and how to think about bridging it without treating working capital as a last resort.
Why Net-60 (and Net-90) Terms Exist
Larger clients — retailers, OEMs, government contractors, distributors — set payment terms based on their own cash management, not yours. Net-60 or net-90 terms let them hold cash longer, and because they’re often the larger, more established party in the relationship, they have the leverage to set those terms as a condition of doing business. For a manufacturer, saying no to those terms often means saying no to the contract. So the terms get accepted, and the cash flow gap becomes something to manage rather than negotiate away.
What the Gap Actually Costs
1. Overtime and Rush Costs to Cover the Timing Squeeze
When cash is tight because of invoices still in the 30-to-90-day window, the easiest lever to pull is often the most expensive one: rushing. A shop that can’t front the material cost for the next job on time ends up paying rush freight to get stock in fast, or authorizing overtime to compress a production schedule that cash constraints delayed starting. Both cost more per unit than the same work done on a normal timeline — and both are a direct, calculable cost of the payment-terms gap, even though they never show up on an invoice labeled “cost of waiting.”
2. Missed Early-Pay Discounts From Your Own Suppliers
Many suppliers offer 1-2% off (or better) for paying within 10-15 days instead of the standard 30. When your own cash is tied up waiting on a client’s net-60 invoice, taking advantage of your supplier’s early-pay discount often isn’t an option — even though it would have been free money if the cash had been available. Over a year of regular purchasing, missed early-pay discounts on raw materials can add up to a real, ongoing cost that’s easy to miss because it never appears as an expense — it just appears as a discount you didn’t get.
3. Strained Vendor Relationships and Worse Terms Over Time
If the cash flow gap causes your own payments to suppliers to slip — even by a few days — that erodes the relationship over time. Suppliers who get paid late start tightening terms, requiring deposits, or moving you down the priority list when materials are scarce. That’s a cost that compounds: it’s not just this month’s friction, it’s a weaker negotiating position on every future order.
4. Capacity You Can’t Use Because Cash Is Tied Up
Perhaps the least visible cost: the job you had to turn down or delay because cash was tied up in receivables from a prior job. A shop operating near its cash ceiling due to a backlog of unpaid net-60 invoices can find itself unable to take on the next contract — not because of a lack of capacity on the floor, but because of a lack of cash to fund the materials and labor to start it. That’s lost revenue that never shows up as a “cost” on any statement, but it’s real.
A Practical Framework for Sizing Your Own Gap
Before treating this as background noise, it helps to put a number on it:
- Map your receivables timeline — how much cash, on average, is sitting in the 30-to-90-day window at any given time across your active invoices?
- Total your rush and overtime spend — over the last two or three quarters, how much went to expedited freight, rush fees, or overtime that was driven by timing rather than the job itself?
- Check your early-pay discount eligibility — are your suppliers offering terms you’re not able to use because cash isn’t available when it’s due?
- Estimate turned-down capacity — has cash timing caused you to delay starting a job, decline a contract, or push back a start date?
Adding these up gives you a real, specific number — not a vague sense that “cash is tight” — and that number is what should be compared against the cost of bridging the gap with working capital.
Working Capital as a Timing Bridge, Not a Bailout
It’s worth being direct about the distinction, because it changes how the decision should be framed. A bailout implies the business is in trouble. A timing bridge means the business is fundamentally sound — the work is done, the invoice is valid, the client is going to pay — and the only problem is that the calendar doesn’t match your obligations. Manufacturers with strong, growing order books are often the ones who feel this gap the most, precisely because more business means more cash parked in receivables at any given moment.
Funding used this way is meant to cover the interval between completing work and getting paid for it — not to prop up a business that can’t otherwise sustain itself. That distinction matters both for how you think about the decision and for how a lender evaluates it.
How the Direct Fund Program Fits
Smart Business Funding’s Direct Fund Program is built to bridge exactly this kind of timing gap. Manufacturing and production businesses can access funding from $10,000 to $5,000,000, with underwriting typically completed in one to five hours and funding available as fast as the same or next business day — timing that matters when payroll or a supplier payment is due well before a client’s net-60 invoice clears.
Repayment is structured as a fixed daily or weekly remittance — a known, set amount rather than a percentage tied to your incoming receivables. That predictability is useful specifically because it lets you plan around the gap instead of layering more uncertainty on top of it. Full program details are available on the Merchant Cash Advance page.
Businesses with at least one year in operation, $50,000 or more in monthly revenue, and a credit score around 500 or higher (soft pull only, so checking eligibility doesn’t affect your credit) can typically get a straightforward answer on qualification.
If the timing gap is recurring — the same net-60 or net-90 pattern shows up with every large client — it’s also worth comparing a one-time funding amount against a line of credit, which is built for exactly that kind of repeat, ongoing gap rather than a single purchase. And if the pressure point is less about payment timing and more about aging equipment slowing down the jobs that create these invoices in the first place, equipment financing is worth reviewing separately.
This Pattern Shows Up Across Manufacturing and Production Sectors
Contract manufacturers working with large OEMs, metal fabricators supplying construction and infrastructure projects, and industrial suppliers working with government contracts all tend to see the longest standard terms — often net-60 or net-90 by default rather than by negotiation. Smaller producers selling into big-box retail distribution channels see a similar pattern. You can review how funding applies to your specific sector on the Industries page.
Why Manufacturers Work With Smart Business Funding
Smart Business Funding (Collins Cash Inc. d/b/a Smart Business Funding) has funded businesses across all 50 states since December 2014 and holds an A+ rating with the Better Business Bureau, a five-star average on Trustpilot, and was named to the Inc. 5000 list of fastest-growing private companies in 2020. The company has funded more than $500 million to businesses nationwide, including manufacturers navigating exactly this kind of payment-timing gap.
Ready to Bridge the Gap on Your Next Net-60 Invoice?
If payroll or a supplier payment is due before a client’s invoice clears, apply now to see what you qualify for — with no impact to your credit to check.
Want to talk through how funding could line up with your specific receivables timeline? Contact us or call 1-866-Re-Smart to walk through it with our team.
Frequently Asked Questions
Is it a bad sign if my business needs funding to cover net-60 payment terms? No — it’s a common structural issue for manufacturers working with larger clients who set their own payment terms. A strong order book with growing receivables can create this exact gap even when the underlying business is healthy.
What’s the real cost of waiting on a net-60 invoice? Beyond the delay itself, the cost shows up as rush freight and overtime to compress schedules, missed early-pay discounts from your own suppliers, strained vendor relationships if your own payments slip, and capacity you can’t use because cash is tied up in unpaid invoices.
How is working capital for a payment-terms gap different from a loan? Funding through the Direct Fund Program is structured as a fixed daily or weekly remittance, not a traditional loan with an interest rate — repayment is a known, set amount rather than a shifting figure.
How quickly can a manufacturer get funded to bridge a net-60 gap? Underwriting typically takes one to five hours, with funding available same-day or next-day in many cases — timing built around exactly this kind of gap between completing work and getting paid.
Should I use a line of credit or a one-time funding amount for this problem? If the net-60 or net-90 gap is a recurring pattern with your regular clients, a line of credit may fit better than repeatedly applying for one-time funding. If it’s a single large invoice creating a temporary squeeze, a one-time Direct Fund Program advance may be the simpler fit.
About the Author
Anthony Collin is the CEO of Smart Business Funding (Collins Cash Inc.), a direct funding provider that has worked with manufacturing, production, and small business owners across all 50 states since December 2014. Smart Business Funding holds an A+ Better Business Bureau rating and a five-star Trustpilot average, and was named to the Inc. 5000 in 2020.