Same-Day Business Funding: How Fast Can You Actually Get Funded?
Search “same day business funding” and you’ll get a wall of ads promising instant approval and money in your account before lunch. Some of that is real. A lot of it isn’t. The honest answer is that funding speed depends on a handful of specific, knowable factors — and once you understand them, you can actually predict how fast your own application will move, instead of hoping an ad’s headline applies to you.
This isn’t a case against fast funding — it’s a case for understanding what “fast” is actually built on, so you’re not caught off guard when a “24 hour business funding” ad turns into a two-week process.
What Actually Determines Funding Speed
1. How complete your submission is on day one. This is the single biggest lever. Most delays don’t come from underwriting — they come from a missing bank statement, an incomplete application field, or a document that needs to be re-sent. A funder reviewing a complete file can move in hours. A funder chasing down paperwork can’t.
2. Revenue consistency. Underwriters move faster on businesses with a clear, steady deposit pattern. That doesn’t mean perfect — seasonal dips and slow months are normal — but a business with erratic, hard-to-read cash flow will typically take longer to underwrite than one with a legible pattern, even if the total revenue is similar.
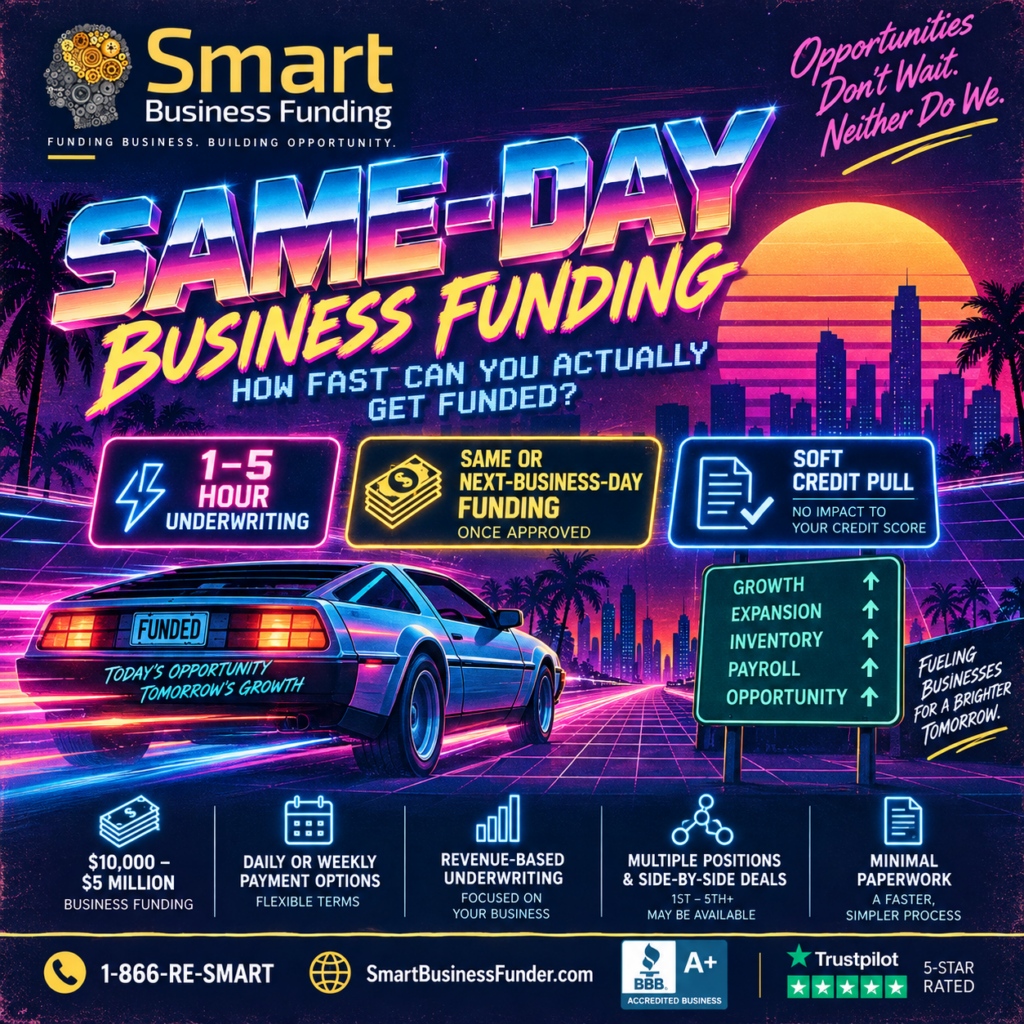
3. Whether the credit check is a soft or hard pull. A soft credit pull, like the one used for Smart Business Funding’s Direct Fund Program, doesn’t add a hard inquiry to your credit file and generally moves faster than a review requiring a full credit report pull.
4. Existing funding positions. Businesses already carrying financing can still qualify for additional positions (1st through 5th+, including side-by-side structures) — this affects how the new funding is sized and structured more than how fast it’s reviewed, but it’s part of the underwriting picture.
5. Business type and industry. Some industries require a slightly closer underwriting look due to historical performance data for that category. That’s a pricing and risk input, not a judgment about your specific business, but it can add a small amount of review time.
A Realistic Timeline (Not a Marketing Timeline)
With a complete application for the Direct Fund Program — bank statements, application details, and documentation all submitted upfront — underwriting review typically takes 1 to 5 hours, with funding arriving as soon as the same or next business day once approved. That’s the range worth planning around: not “instant,” and not “next week,” but a same-day-to-next-day window driven by how ready your paperwork is.
Compare that to language like “immediate business funding” or “24 hour business funding” — those phrases usually describe the best-case scenario for the cleanest possible application, not a guarantee. Asking a funder directly what their typical timeline is, and what could slow it down, tells you more than any ad headline.
How to Actually Speed Up Your Own Funding Timeline
- Gather your last 3–6 months of bank statements before you apply, not after being asked for them.
- Know your numbers going in — average monthly revenue, time in business, and any existing funding positions — so there’s no back-and-forth clarifying basic facts.
- Respond immediately to any follow-up request. A same-day turnaround on your side of the paperwork is often the difference between funding today and funding in three days.
- Ask about qualification before applying, so you’re not waiting on a decision for a business that doesn’t yet meet the baseline: $50,000+ in monthly revenue, one year in business, and a credit minimum around 500.
Illustrative Composite Scenario (not an actual client, for explanatory purposes only): An HVAC repair company submits a complete application with six months of clean bank statements on a Tuesday morning. Underwriting review is completed by early afternoon, and funding is deposited the same business day — largely because there was no missing documentation to chase down.
When “Fast” Isn’t the Only Thing That Matters
Speed is important, but it shouldn’t be the only filter. A fast approval on terms you don’t fully understand isn’t actually a win. Before accepting any offer — fast or otherwise — confirm the total repayment amount, the fixed daily or weekly remittance schedule, and how the factor rate was calculated. The how it works page walks through the Direct Fund Program structure in full before you apply.
How Smart Business Funding Approaches Speed
The Direct Fund Program funds $10,000 to $5,000,000 across terms of 2–10 months, with underwriting built around actual business revenue rather than a lengthy manual credit review. Explore funding options by business type on the industries page, or if your documentation is ready, go straight to the application.
Frequently Asked Questions
Is same-day business funding actually real? Yes, but it depends on how complete your application is. With clean, ready documentation, Direct Fund Program underwriting typically takes 1–5 hours, with funding arriving as soon as the same or next business day.
What’s the biggest thing that slows down funding? Incomplete or missing documentation, most commonly bank statements — not the underwriting decision itself.
Does a soft credit pull affect my score? No — a soft pull, like the one used for Direct Fund Program qualification, does not add a hard inquiry to your credit file.
Can I qualify for fast funding with existing financing in place? Often yes — additional funding positions (1st through 5th+) are available, though they affect sizing and structure rather than speed specifically.
What do I need ready to move as fast as possible? Your last 3–6 months of bank statements, basic business details, and a clear picture of your average monthly revenue and time in business.
Have your documentation ready and want to see how fast your specific numbers could move? Apply now or call 1-866-Re-Smart. You can also reach the team via contact us.