
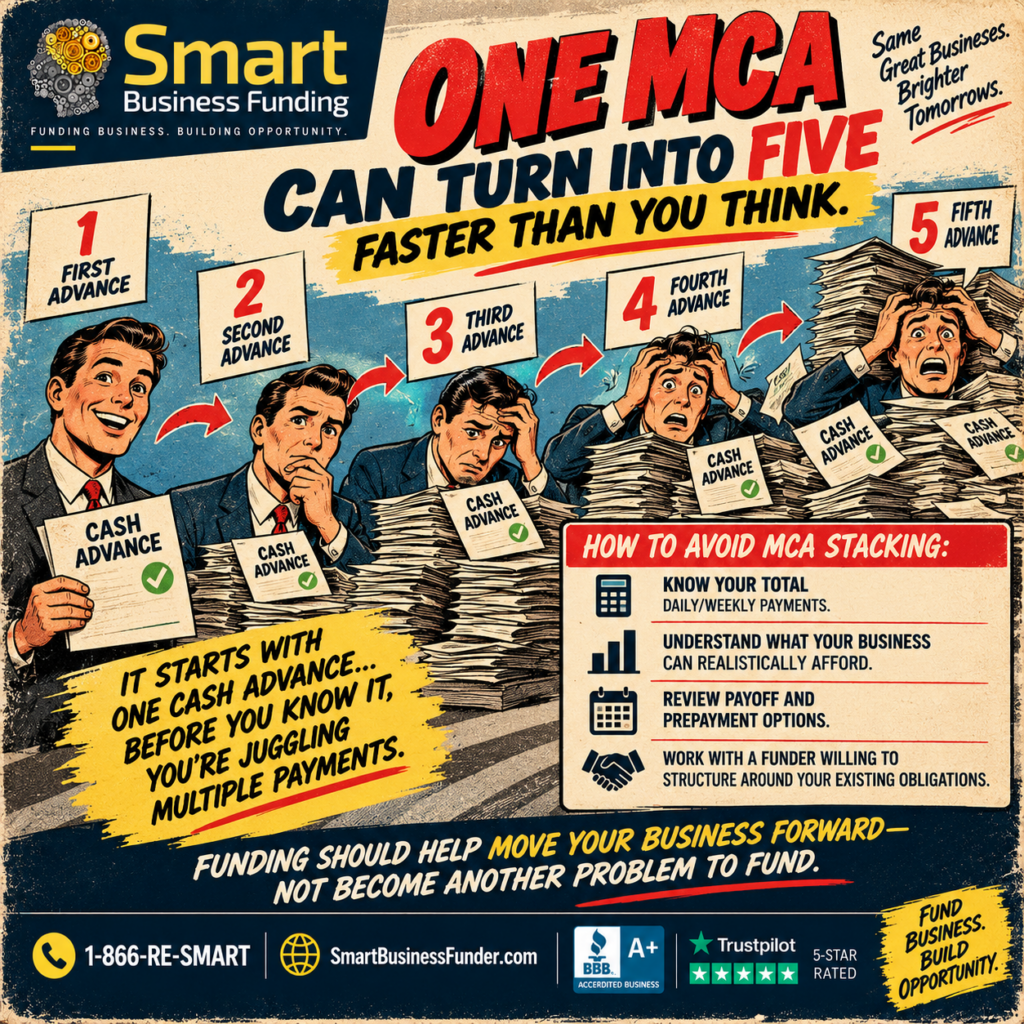
MCA Stacking: How One Cash Advance Turns Into Five (And How to Avoid It)
Merchant cash advance defaults surged 59% to $2.22 billion in 2024, and businesses juggling multiple simultaneous advances default at three to five times the rate of businesses carrying just one. Attorneys who handle small business bankruptcies increasingly describe MCA funders as recurring creditors in these cases — and rarely just one. The pattern behind almost all of it has a name: stacking.
Understanding exactly how stacking happens — and how it’s different from a business deliberately using more than one funding position as part of a planned strategy — is the difference between using this kind of financing safely and ending up in the situation these statistics describe. If you’re trying to figure out whether an existing funding decision fits your business safely, our guide on what to actually qualify for before applying is a useful starting point before adding any additional position.
What Stacking Actually Is
Stacking happens when a business takes on a second cash advance specifically to cover the daily or weekly payments on a first advance that’s already straining its cash flow — and then, often, a third to cover the second. Each new advance places another claim against the same future revenue stream the business is already committing to its existing obligations. The business isn’t funding new growth or covering a new, separate need; it’s borrowing to service what it already owes.
This is meaningfully different from a business that takes a second, planned funding position — for a genuinely separate need, sized deliberately, with the combined repayment obligation modeled against actual cash flow from the outset. Structured multiple-position funding, including side-by-side arrangements, is a legitimate and common part of how revenue-based funding works. What turns this into a problem isn’t the number of positions on its own — it’s whether each position was taken proactively, for a real and separate need, or reactively, to patch a hole the last advance created.
How the Pattern Actually Unfolds
The progression tends to follow a recognizable shape:
- A first advance is taken, often for a legitimate and well-defined need, at a repayment amount that seemed manageable at the time.
- Revenue underperforms the plan slightly — a slow month, a client delay, a seasonal dip — and the fixed daily or weekly repayment starts to feel tight against actual incoming cash.
- A second advance is taken, not to fund something new, but specifically to keep up with the first advance’s payments.
- The combined repayment obligation from both advances now exceeds what the original plan accounted for, and the cycle repeats — a third advance covering the gap created by the second.
- By the time the business recognizes the severity of the pattern, it may still be making every scheduled payment while losing the actual capacity to meet payroll, purchase inventory, or pay vendors.
Industry analysts note that the specific number of positions matters diagnostically: one advance with misaligned terms may be a contained, fixable problem; two positions can sometimes still be resolved with a deliberate restructuring; but a business carrying four or five active advances has typically progressed well past a discrete payment problem into a capital structure that depends on repeated high-cost borrowing just to stay current.
Why This Pattern Is So Easy to Fall Into
MCAs are fast and don’t require the collateral or lengthy credit history a bank product does — which is exactly what makes them useful for a genuine timing gap, and exactly what makes it tempting to reach for a second one when the first starts to strain. There’s no formal underwriting gatekeeper stopping a business from taking on more obligation than it can actually support, the way a bank’s debt-to-income calculation might. That flexibility is a real benefit when used deliberately — it’s also the mechanism that makes reactive stacking possible in the first place.
The Warning Signs Before It Becomes a Structural Problem
- A new advance is being considered specifically to cover an existing advance’s payments — not a new business need. This is the clearest single signal that a business has crossed from planned funding into reactive stacking.
- Repayment obligations are consuming a growing share of daily revenue compared to when the first advance was taken, without a corresponding increase in overall business revenue.
- The business is current on every payment but can’t meet payroll, vendor payments, or tax obligations on schedule — a sign that funding is being serviced at the expense of operations rather than alongside them.
- Each new position is smaller and shorter-term than the last, often a signal that available financing options are narrowing as risk increases.
How to Avoid the Pattern in the First Place
- Size any advance to the actual, quantified need — not the maximum available. Our piece on sizing funding correctly for a specific cash flow gap walks through this principle in the context of a slow-paying client, but the same discipline applies to any funding decision.
- Model the full repayment obligation against your actual revenue before signing — not your best month, and not a projected recovery that hasn’t happened yet.
- Treat a second position as a deliberate decision for a separate need, not a reflexive response to the first one feeling tight. If the honest reason for a new advance is “to cover the last one,” that’s the signal to stop and reassess rather than proceed.
- Ask directly about total combined repayment obligation if you’re considering an additional position alongside an existing one, so the full picture — not just the new advance in isolation — is what you’re deciding against.
Illustrative Composite Scenario (not an actual client, for explanatory purposes only): A retail business takes a well-sized advance to fund a seasonal inventory purchase, with repayment fully modeled against expected sales. A slower-than-expected sales season leaves the daily repayment tighter than planned. Rather than taking a second advance to cover the shortfall, the business revisits its sizing assumptions and works directly with its funder to understand available options given the actual revenue picture — avoiding the reactive step of stacking a new advance on top of the first.
If You’re Already Carrying Multiple Positions
If you’re evaluating an existing set of multiple advances rather than considering a new one, the first step is an honest assessment of whether each position reflects a genuine, separate business need or whether later positions were taken to service earlier ones. That distinction shapes what kind of solution actually fits — and it’s a conversation worth having directly with your funder or a qualified advisor before taking on any additional obligation.
How Smart Business Funding Approaches Funding Sizing
Smart Business Funding’s Direct Fund Program is built around a fixed factor rate and a fixed daily or weekly repayment schedule disclosed before you sign, so the full obligation is known upfront rather than discovered under pressure later. See the full process on the how it works page, and if you’re weighing multiple funding needs, our guide to types of business funding ranked by speed can help you think through which need actually calls for a new position versus a different tool entirely.
Frequently Asked Questions
What exactly is MCA stacking? Stacking is taking a new cash advance specifically to cover the payments on an existing advance, rather than to fund a separate, genuine business need — creating a cycle of increasing obligation against the same revenue.
Is having more than one active cash advance always a problem? Not necessarily — deliberately structured multiple positions for genuinely separate needs, sized against actual revenue from the outset, are a normal part of revenue-based funding. The risk comes specifically from reactive stacking.
How can I tell if I’m at risk of stacking? The clearest warning sign is considering a new advance specifically to make payments on an existing one, rather than to fund something new.
Why do MCA defaults happen more often with stacked positions? Each additional position places another claim against the same revenue stream, and the combined obligation can exceed what the business can sustain while still covering payroll, vendors, and other operating costs.
What should I do if I think I’m already stacking? Get an honest, complete picture of your combined repayment obligations against actual revenue, and talk directly with your funder or a qualified advisor before taking on any additional position.
Weighing a new funding decision and want to make sure it’s sized correctly? Apply now or call 1-866-Re-Smart to talk through the full picture. You can also reach the team at contact us.

