
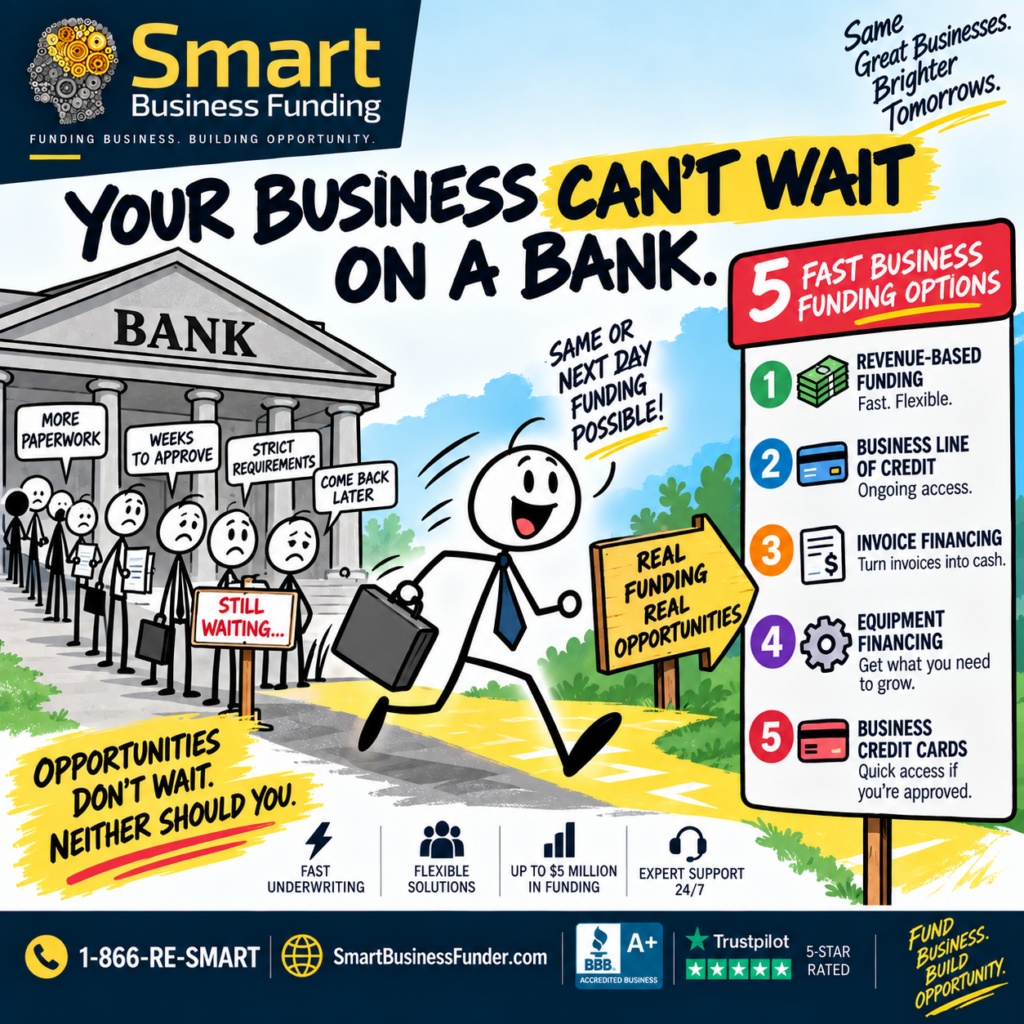
5 Fast Business Funding Options for Companies That Can’t Wait on a Bank
A bank might genuinely offer the lowest rate on paper. It also might take six weeks to get there — and six weeks doesn’t help if payroll is due Friday or a piece of equipment fails this week. This list isn’t about which option is objectively “better” in every situation. It’s about which options are actually built for speed, and what each one requires from you to move fast.
1. Revenue-Based Funding (Fastest Overall)
Revenue-based funding, like Smart Business Funding’s Direct Fund Program, evaluates a business’s actual monthly revenue and deposit consistency rather than leading with a lengthy credit and collateral review. With a complete application, underwriting typically takes 1–5 hours, and funding can arrive as soon as the same or next business day. Funding ranges from $10,000 to $5,000,000, with a fixed factor rate (1.25–1.49 standard-risk, 1.359–1.499 higher-risk) producing a disclosed total repayment amount, repaid on a fixed daily or weekly schedule. Qualification centers on $50,000+ in monthly revenue, one year in business, and a credit minimum around 500 evaluated with a soft credit pull.
What to watch for: Size the funding to your actual need rather than the maximum you qualify for — repayment draws from overall business revenue on a fixed schedule, so it should be sized against your full cash flow picture, not just the specific gap.
2. Business Line of Credit
A business line of credit gives you revolving access to capital you draw against as needed, which is especially useful if your cash flow gaps are recurring rather than one-time. Initial underwriting takes some time, but once approved, subsequent draws are typically fast, since the credit relationship is already established. Smart Business Funding’s lines of credit are built around exactly this kind of ongoing access.
What to watch for: A line of credit is a better fit for a pattern than a single event — if you only need funding once, a one-time product may be more direct.
3. Equipment Financing
When the need is a specific piece of equipment, financing secured by that equipment can move faster than an unsecured product because the underwriting has a clear, valuable asset to evaluate. Smart Business Funding’s equipment financing is designed for exactly this scenario — a vehicle, a piece of machinery, kitchen equipment, or similar.
What to watch for: This option only fits when the funding need is tied directly to equipment; it’s not a general-purpose solution for payroll, inventory, or invoice gaps.
4. Business Credit Cards
For smaller, immediate needs, a business credit card is often the fastest option to actually use once approved — sometimes within days of applying, and usable the moment the card arrives. The tradeoff is a generally lower limit and a variable APR that moves with broader interest rate conditions, which is worth watching closely given the Fed’s recent rate hike and signaled additional increases this year.
What to watch for: Credit cards work well for smaller, short-term float — they’re rarely the right tool for a larger, one-time capital need like equipment or a significant payroll gap.
5. Invoice-Timing-Specific Funding
When the issue is specifically a slow-paying client rather than an overall revenue shortfall, funding sized to bridge that exact gap — rather than the entire outstanding invoice — is often the fastest and most precisely-targeted option. This is a scenario the Direct Fund Program is commonly used for, though it’s worth understanding clearly that repayment runs on a fixed schedule from your overall revenue rather than pausing until the specific invoice clears; our full breakdown in Your Biggest Customer Is Late Paying: How Do You Cover the Gap? covers exactly how to size this correctly.
What to watch for: Confirm directly with any funder whether repayment structure is truly fixed or tied to the invoice timeline — those are very different risk profiles, and it’s an easy detail to misunderstand under time pressure.
How These Five Compare on Speed and Fit
| Option | Typical Speed | Best Fit |
|---|---|---|
| Revenue-based funding | Hours to 1 business day | Urgent, one-time gaps |
| Business line of credit | Fast after initial setup | Recurring or unpredictable needs |
| Equipment financing | Days | Asset-specific purchases |
| Business credit cards | Days | Small, short-term float |
| Invoice-timing funding | Hours to 1 business day | Bridging a specific slow-paying client |
What Actually Determines How Fast You Get Funded
Across nearly all of these options, the biggest lever isn’t the product — it’s how prepared your documentation is. Missing bank statements or incomplete applications are the most common source of delay, more so than the underwriting decision itself. Our full breakdown of this in Same-Day Business Funding: How Fast Can You Actually Get Funded? covers exactly what to have ready before you apply to any of these options.
Illustrative Composite Scenario (not an actual client, for explanatory purposes only): A commercial cleaning company faces a same-week payroll shortfall caused by a large client’s invoice running a few days behind schedule. A bank line of credit isn’t yet in place, and setting one up would take too long. The owner instead applies for a Direct Fund Program advance sized specifically to the payroll gap, with underwriting completed the same morning and funds arriving the next business day.
If Your Credit Isn’t Perfect
Several of these options — particularly bank-issued products — weigh personal credit heavily. If that’s a concern, revenue-based underwriting takes a different approach, evaluating cash flow ahead of credit history; see Emergency Business Funding With Bad Credit: What Are Your Options? for a full breakdown of how that qualification actually works.
How Smart Business Funding Approaches This
Smart Business Funding offers the Direct Fund Program, lines of credit, and equipment financing — funding businesses across all 50 states since 2014, with underwriting built around business revenue rather than a lengthy bank process. See the full process on the how it works page, review funding by business type on the industries page, or apply now.
Frequently Asked Questions
What’s the fastest business funding option if I can’t wait on a bank? Revenue-based funding, like the Direct Fund Program, is typically the fastest, with underwriting often completed in 1–5 hours and funding as soon as the same or next business day.
Is a business line of credit faster than a one-time advance? Initial setup takes some time either way, but once a line of credit is established, subsequent draws are typically very fast — faster than reapplying for a new one-time product each time.
Do I need strong credit to qualify for these faster options? Not necessarily — revenue-based products weigh monthly revenue and time in business more heavily, with a credit minimum around 500 for the Direct Fund Program.
Can I use fast funding to cover a specific unpaid invoice? Yes, but it should be sized to the actual gap and understood as a fixed repayment obligation from overall revenue, not something that pauses until the invoice clears.
What’s the single biggest thing that speeds up any of these options? Having your documentation — especially bank statements — ready and complete before you apply, since that’s the most common source of delay across nearly every option.
Ready to see which of these fits your timeline? Apply now or call 1-866-Re-Smart. You can also reach the team at contact us.

