
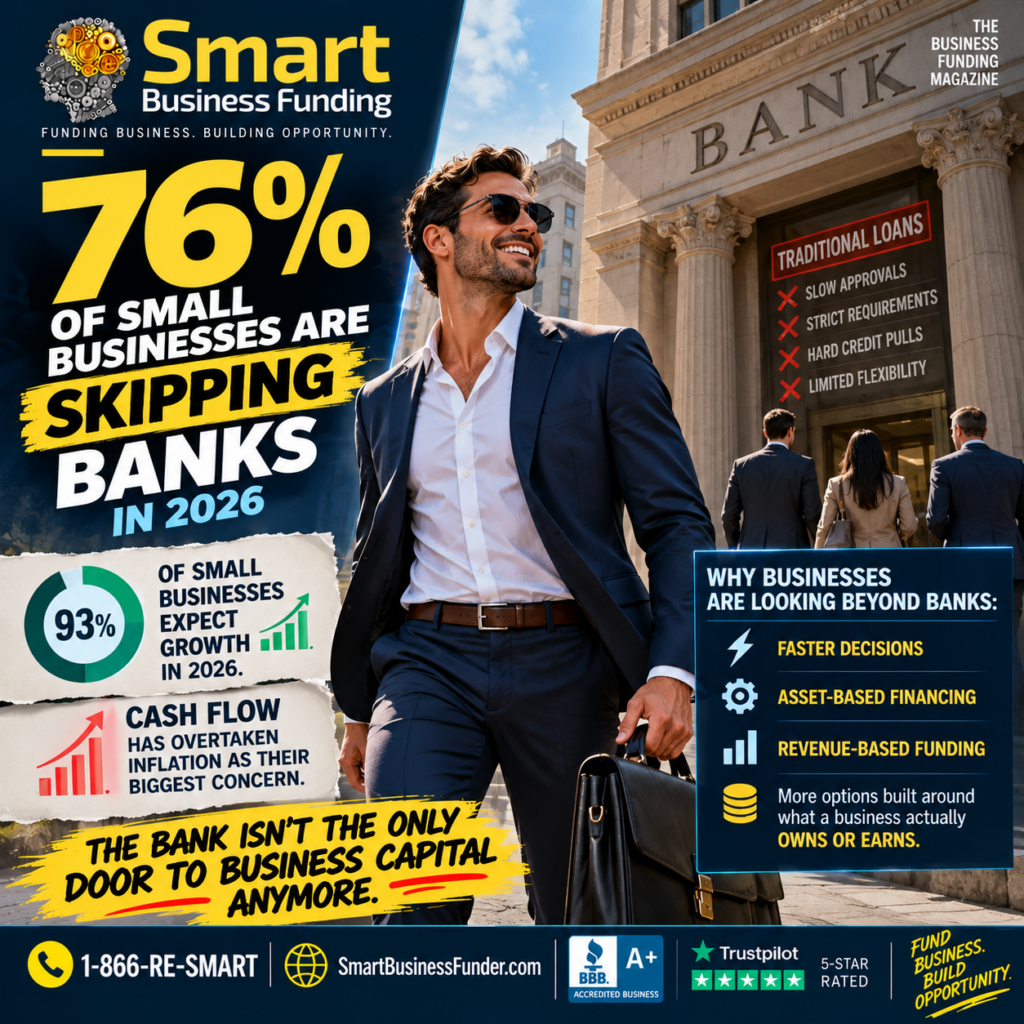
76% of Small Businesses Are Skipping Banks in 2026 — Here’s Where Asset-Based Financing Fits In
A recent small business survey found that more than 76% of small businesses now bypass traditional banks entirely when seeking financing, favoring more flexible alternative options instead. The same survey found cash flow has overtaken inflation as small business owners’ top concern for 2026, even as growth optimism sits at a record high — 93% of respondents expect growth this year, with nearly a third expecting significant growth. Put together, this is a picture of businesses that feel genuinely optimistic about their prospects but are managing that optimism without much reliance on the traditional banking system.
Why This Shift Has Accelerated
The move away from banks isn’t a new trend, but it has clearly intensified. Traditional bank underwriting has remained slow, credit-dependent, and often mismatched to how small businesses actually generate revenue — a gap we’ve covered in detail in our breakdown of why so many line of credit applicants get denied despite record demand, where roughly half of all applicants come away without approval, and approval rates swing by more than 25 percentage points depending on industry alone, as detailed in line of credit approval rates by industry.
Meanwhile, alternative financing has become faster, more sophisticated, and more varied. AI-driven underwriting has made revenue-based qualification decisions that once took days now achievable in hours, and asset-based financing has expanded well beyond its traditional base to cover a much wider range of business types and asset categories.
Where Asset-Based Financing Fits Into This Shift
As businesses move away from banks, asset-based financing has become one of the primary alternative categories filling that gap — particularly for businesses with equipment, inventory, or outstanding invoices to leverage. Our full breakdown in What Is Asset-Based Financing? covers the major categories in depth, but the core appeal is straightforward: a business with a concrete, valuable asset can often access financing through that asset’s value rather than needing to clear a traditional bank’s credit and revenue thresholds.
Where Revenue-Based Funding Fits Into This Shift
For businesses without a specific asset to leverage, revenue-based funding has become the other major pillar of the bank-bypass trend. Products like Smart Business Funding’s Direct Fund Program evaluate a business’s actual cash flow directly, sidestepping both the asset-specific requirements of asset-based financing and the credit-and-collateral-heavy underwriting of a traditional bank product. Our comparison of asset-based financing vs. revenue-based funding covers exactly how to decide between the two based on your specific situation.
Why Cash Flow Has Overtaken Inflation as the Top Concern
It’s a notable shift that cash flow management, rather than inflation itself, is now the leading concern among small business owners. This suggests that even as broader price pressures ease or stabilize, the underlying challenge of managing the timing gap between expenses and revenue remains the more persistent, day-to-day problem for small businesses — a dynamic we’ve covered directly in pieces like what to do when your business can’t make payroll this week and covering the gap from a slow-paying client. It also helps explain why speed, more than headline rate, has become such a central factor in how businesses choose financing — a cash flow gap doesn’t wait for a multi-week bank underwriting process.
What Growth Optimism Alongside Bank Avoidance Actually Signals
The combination of record growth optimism and record bank avoidance is worth sitting with for a moment, because it cuts against an older assumption — that businesses turn to alternative financing mainly out of desperation when a bank says no. This data suggests something closer to a deliberate structural shift: businesses that feel confident about their prospects are choosing faster, more flexible alternative financing proactively, not just as a fallback after being declined elsewhere.
Illustrative Composite Scenario (not an actual client, for explanatory purposes only): A growing landscaping business feels confident about its expansion prospects for the coming year but doesn’t want to commit to a multi-week bank underwriting process for a seasonal equipment purchase. The business instead pursues equipment financing directly, evaluated primarily against the equipment’s own value, while separately using a revenue-based advance for an unrelated short-term cash flow gap — choosing both paths proactively rather than after a bank denial.
What This Means If You’re Still Relying Primarily on Banks
If your business hasn’t yet explored alternatives to traditional bank financing, this data suggests you may be in an increasingly small minority, and potentially missing out on faster, more tailored options that better match how your specific business actually generates value — whether that’s through owned assets or consistent revenue. Our guide to the best business funding options for companies that can’t wait on a bank is a practical starting point for evaluating what’s actually available beyond a traditional bank application.
How Smart Business Funding Fits Into This Shift
Smart Business Funding offers both asset-based options — equipment financing and ongoing lines of credit — and the revenue-based Direct Fund Program, funding businesses across all 50 states since 2014 with underwriting built around what your business actually owns or earns, rather than a traditional bank’s credit-first model. See the full process on the how it works page, review funding by business type on the industries page, or apply now.
Frequently Asked Questions
Why are so many small businesses bypassing banks for financing in 2026? Slow, credit-dependent bank underwriting has increasingly mismatched how small businesses actually generate revenue, while alternative financing has become faster and more sophisticated, offering both asset-based and revenue-based paths to qualification.
Is bypassing banks a sign of financial distress? Not necessarily — current data shows record small business growth optimism alongside record bank avoidance, suggesting many businesses are choosing alternatives proactively rather than only after being denied elsewhere.
Why has cash flow overtaken inflation as the top concern? It suggests that even as broader price pressures stabilize, the day-to-day challenge of timing gaps between expenses and revenue remains the more persistent issue for small businesses.
What’s the difference between the two main alternatives to bank financing? Asset-based financing qualifies you based on a specific owned asset, while revenue-based funding qualifies you based on your business’s actual cash flow — the right fit depends on your specific situation.
How do I know if my business should move away from relying on banks? If your funding needs are time-sensitive, tied to a specific business asset, or don’t fit neatly into a traditional bank’s credit-first underwriting model, it’s worth evaluating both asset-based and revenue-based alternatives directly.
Ready to see how your business’s assets or revenue could unlock faster funding? Apply now or call 1-866-Re-Smart. You can also reach the team at contact us.

