Your Biggest Customer Is Late Paying: How Do You Cover the Gap?
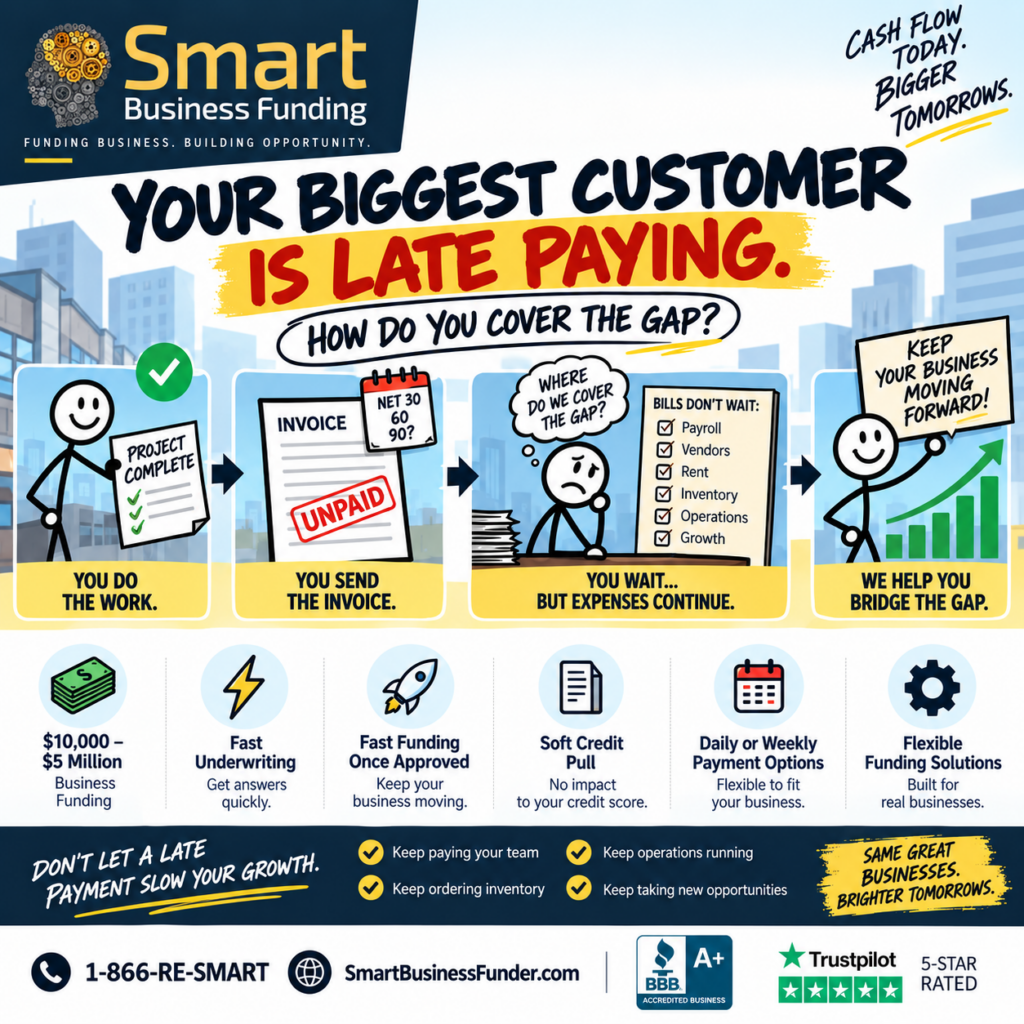
There’s a particular kind of frustration that comes from a cash flow problem you didn’t cause. You did the work. You sent the invoice. The client isn’t disputing it — they’re just slow. And while you wait, your own payroll, rent, and vendor payments are still due on schedule.
A late-paying customer, especially a large one, can put real financial pressure on a business that is otherwise completely healthy. This is one of the most common ways a profitable company still ends up short on cash — and it’s a different problem than a revenue shortfall, which means it usually has a different solution.
First, Figure Out What Kind of “Late” You’re Dealing With
Not all late invoices are the same problem:
- Confirmed but delayed. The client has acknowledged the invoice and payment is processing — this is a pure timing issue.
- Chronically slow. The client always pays late, every cycle, as a pattern — this is a structural issue, not a one-time gap.
- Going quiet. No response, no confirmation — this is a collections risk, and it needs a different response entirely (documentation, formal follow-up, potentially legal escalation) rather than a funding conversation.
The first two are what this guide focuses on, because they’re solvable with the right financing approach. The third needs to be handled as its own issue first.
Size the Actual Gap — Not the Whole Invoice
A common mistake is assuming you need funding equal to the entire outstanding invoice. In reality, if the rest of your revenue is flowing normally, you likely only need to cover the specific shortfall between what’s due on your end and what’s currently available. Modeling this precisely — rather than reflexively seeking financing for the full receivable — keeps any funding sized appropriately to the actual problem.
How Financing Actually Works Against This Gap
This is the part worth understanding clearly, because it’s often misunderstood: with Smart Business Funding’s Direct Fund Program, repayment is a fixed daily or weekly remittance drawn from your overall business revenue — it is not structured to pause until the specific late invoice clears. That means:
- The advance bridges the timing gap, giving you working capital now while you wait on the client payment.
- Repayment continues on its fixed schedule regardless of exactly when that one invoice lands, funded by your business’s overall incoming revenue.
- Sizing matters more here than almost anywhere else — because repayment draws from your full cash flow, not just the invoice in question, it’s important to size the advance against what your business can comfortably repay overall, not just against the receivable you’re waiting on.
This is exactly why talking through the numbers with a funding specialist before applying is worth the extra ten minutes — it’s the difference between an advance that smooths the gap and one that creates a new pressure point.
Options Depending on Whether This Is a One-Time or Recurring Problem
If this is a one-time gap (a single large client running behind for the first time), a short-term advance from the Direct Fund Program — ranging from $10,000 to $5,000,000 with terms of 2–10 months — sized specifically to the shortfall is typically the most direct fix.
If this is a recurring gap (the same client, or the nature of your business, consistently creates a receivables lag), a line of credit is often a better structural fit. Rather than reapplying every time the same pattern shows up, a standing line is available on demand for exactly this kind of recurring timing mismatch.
Illustrative Composite Scenario (not an actual client, for explanatory purposes only): A commercial cleaning company bills its largest client, a property management firm, on net-45 terms. The client is reliable but consistently slow, creating a recurring 7–10 day gap each cycle between when the cleaning company’s own vendor and payroll obligations come due and when that invoice actually lands. Rather than repeatedly seeking one-off funding, the business sets up a revolving line of credit sized to the recurring gap.
What to Watch Out For
- Don’t fund the full invoice amount by default. Model the actual shortfall first.
- Don’t assume repayment pauses for your situation. Confirm directly with any funder whether repayment is truly fixed on a schedule or contingent on invoice timing — the two are very different structures with very different risk to you.
- Don’t wait until the gap becomes a crisis. A confirmed but delayed invoice is much easier to bridge calmly than a payroll deadline that’s two days away.
How Smart Business Funding Approaches Receivables Gaps
Smart Business Funding has funded businesses across all 50 states since 2014, offering both the Direct Fund Program for one-time gaps and lines of credit for recurring ones. Review the full process on the how it works page, see funding built around your specific business type on the industries page, or apply now to talk through your numbers.
Frequently Asked Questions
Can I get funding specifically because a client hasn’t paid me yet? Yes — this is one of the most common reasons businesses use short-term funding: bridging the gap between confirmed but delayed receivables and current obligations.
Does repayment pause until the invoice is paid? No — repayment on the Direct Fund Program runs on a fixed daily or weekly schedule from your overall business revenue, independent of when the specific invoice clears. Any advance should be sized with that in mind.
How much funding do I actually need for a late invoice? Typically the specific shortfall between what’s due and what’s available — not the full invoice amount — assuming the rest of your revenue is flowing normally.
What if the same client is late every single cycle? A recurring pattern is usually better solved with a standing line of credit than repeated one-time advances, since it’s available on demand each time the gap recurs.
What if the client isn’t just late, but unresponsive? That’s a collections issue rather than a timing issue, and it typically needs documentation and formal follow-up (and potentially legal guidance) before a funding conversation makes sense.
If a slow-paying client is putting pressure on your cash flow, apply now or call 1-866-Re-Smart to talk through how to size it correctly. You can also reach the team at contact us.