Women Are 41% of Lawyers but Only 28% of Partners — Here’s the Capital Gap Nobody’s Pricing In
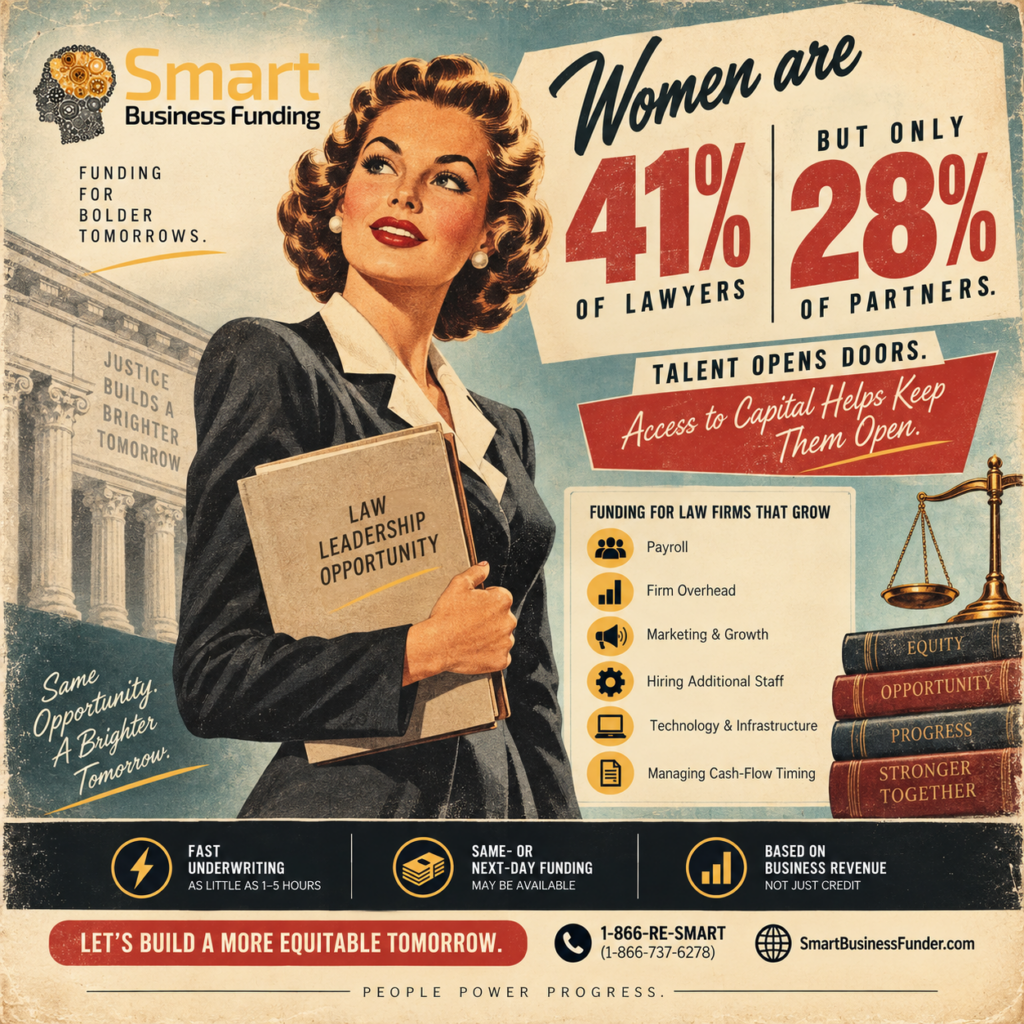
Women make up 41% of lawyers in the United States. But when you look at who actually holds equity partnership at law firms, that number drops to 28%. Something happens between “associate” and “partner” that isn’t happening equally for men and women.
Most conversations about this gap focus on hours, mentorship, and who gets the best client assignments. Those things matter. But there’s a piece of the story that gets skipped almost every time: partnership often costs money up front, and that cost isn’t small.
What a Buy-In Actually Is
At many law firms, becoming an equity partner isn’t just a promotion. It’s a purchase. New partners are often asked to contribute capital to the firm — sometimes tens of thousands of dollars, sometimes far more, depending on the firm’s size and structure. This buy-in helps fund the firm’s working capital, covers a share of its overhead, and gives the new partner an ownership stake instead of just a bigger paycheck.
For someone with savings, home equity, or family wealth to draw on, a buy-in is a hurdle, but a clearable one. For someone without those resources, it can be the difference between making partner and staying an associate or counsel indefinitely, no matter how strong their book of business is.
This is where the numbers start to matter. Women in law, on average, carry more student debt than men and reach senior roles later relative to men with similar experience, based on broader labor market patterns tracked by the Bureau of Labor Statistics. Add a five- or six-figure buy-in requirement on top of that, and a real financial bottleneck starts to take shape — one that has nothing to do with legal skill and everything to do with access to capital at the exact moment a career decision needs to happen.
Why This Gap Doesn’t Show Up in the Usual Data
Law firms don’t publish buy-in requirements. There’s no public database tracking how much capital a new partner needs at any given firm, let alone how that number breaks down by gender. What we do have is the outcome: 41% of lawyers are women, but only 28% of partners are. The cause is almost certainly a mix of factors — client development time, parental leave timing, informal sponsorship networks — and a buy-in requirement is one piece that’s rarely named out loud.
That’s worth being honest about. This isn’t a claim that capital access is the only reason for the partnership gap, or even the biggest one. It’s a claim that it’s a real factor, it’s measurable in principle, and almost nobody is talking about it as a financing problem with a financing solution.
Why Traditional Financing Doesn’t Solve This Well
If a lawyer needs to fund a buy-in, the obvious first move is a personal loan or a line of credit from a bank. In practice, that path has real friction:
Banks look at personal assets, not future partnership income. A bank evaluating a personal loan application weighs your current savings, your home equity, and your existing debt. It generally doesn’t weigh the fact that your partnership stake will start generating real income the moment you close the deal. That mismatch hits harder for someone earlier in their asset-building years, or someone who took on more debt getting through law school.
Firm-arranged financing isn’t universal. Some firms have relationships with banks that offer buy-in loans to incoming partners, sometimes with the firm co-signing or guaranteeing part of the loan. But this isn’t standard across the industry, and it depends heavily on the firm’s size, its banking relationships, and its willingness to extend that support to every partner class equally.
Timing rarely lines up. A partnership offer often comes with a deadline. Arranging traditional financing, especially without an existing relationship with a lender, can take weeks — time a candidate may not have if the firm expects an answer, and a capital contribution, on a set schedule.
What This Looks Like in Practice
The following is an illustrative composite scenario built to demonstrate a common situation — it does not represent an actual funded client, and figures are illustrative only, not a guarantee of terms, approval, or outcome for any specific business.
Picture a senior associate at a mid-sized firm, ten years in, with a strong book of business and a partnership offer on the table. The buy-in is $75,000, due within 90 days of accepting. She doesn’t have that much sitting in savings — most of her early career earnings went toward paying down law school debt, not building a cash cushion. Her male peer, offered partnership the same year, has a smaller version of the same problem, but a parent willing to help bridge the gap. She doesn’t have that option.
She could ask the firm for a longer payment timeline, and some firms will negotiate. But if the firm won’t budge, and a bank loan won’t close in time, the practical result is a choice between turning down partnership or scrambling for capital under real time pressure. That’s not a hypothetical rare case. It’s a plausible version of what happens every time a buy-in deadline collides with a financing timeline that doesn’t move fast enough.
Where Alternative Funding Fits — and Where It Doesn’t
This isn’t a case for treating alternative business funding as a substitute for a well-structured personal or firm-arranged buy-in loan when time allows for one. Anyone facing a partnership buy-in decision should talk to a financial advisor and, ideally, negotiate directly with the firm about payment terms before looking at outside financing at all.
Where a product like Smart Business Funding’s Direct Fund Program can fit is narrower and more specific: for an attorney who already owns or co-owns a practice — solo practitioners, small firm partners, or boutique firm owners — the Direct Fund Program can fund working capital needs tied to the business itself, underwritten against the practice’s existing revenue rather than a buy-in structure, with same- or next-day funding and repayment as a fixed daily or weekly remittance. It is not built to fund an incoming associate’s buy-in into a firm they don’t yet own a piece of, and it shouldn’t be positioned that way.
What this piece is really pointing at is a market gap: a fast, revenue-based, or asset-light financing product built specifically for law firm buy-ins doesn’t widely exist yet, and the lawyers most affected by that gap are disproportionately the ones for whom traditional financing already works worse.
What Firms and Candidates Can Actually Do
If you’re a firm evaluating your buy-in structure: consider whether your payment terms are creating an invisible filter on who can accept a partnership offer, regardless of merit. A longer timeline, a tiered structure, or a firm-backed financing option can remove a barrier that has nothing to do with legal talent.
If you’re a candidate facing a buy-in deadline: ask about payment timeline flexibility before assuming the number on the table is fixed. Firms negotiate buy-in terms more often than most candidates realize, particularly for a partner they clearly want to keep.
If you’re already a practice owner facing a working capital gap unrelated to a partnership buy-in — payroll, overhead, or a cash flow timing issue in your existing practice — that’s a problem revenue-based funding is actually built to solve, and worth a direct conversation rather than assuming a slow bank product is the only option.
The Gap Worth Naming
Women are 41% of lawyers and 28% of partners. Nobody thinks that gap has one single cause, and this piece isn’t claiming it does. But a five- or six-figure buy-in requirement, evaluated by traditional lenders who weigh personal assets over future partnership income, is a real and measurable piece of the story — and it’s one almost nobody prices into the conversation about why partnership parity hasn’t arrived yet.
Own or co-own a law practice and facing a working capital need? Apply now or call 1-866-Re-Smart to speak with our team.
FAQs
Q: Can business funding be used to pay a law firm partnership buy-in? A: The Direct Fund Program is built for practice owners with existing business revenue, not for funding an incoming associate’s buy-in into a firm they don’t yet hold equity in. Buy-in financing is better handled through a personal loan, firm-arranged financing, or direct negotiation with the firm.
Q: Why do fewer women make partner than the share of women in the legal profession would predict? A: The reasons are varied and include client development time, parental leave timing, and access to sponsorship. Access to buy-in capital is one measurable, underdiscussed factor among several.
Q: What financing options exist for law firm partnership buy-ins? A: Options include personal savings, personal loans or lines of credit, and firm-arranged financing where available. Not all firms offer the last option, and terms vary widely by firm size and structure.
Q: Does Smart Business Funding offer financing for law firm partnership buy-ins? A: No. The Direct Fund Program is designed for working capital needs of an existing law practice, underwritten against that practice’s own revenue — not for capital contributions into a firm the applicant does not yet own.