America’s Contractors Are Aging Out: Who Will Build What Comes Next?
America needs contractors.
Homes need to be built and renovated. Roads and infrastructure need repairs. Commercial properties need improvements. Manufacturers need facilities. Businesses need electricians, plumbers, HVAC technicians, roofers, concrete contractors, welders, masons, and other skilled trades.
But behind that demand is a demographic shift that could reshape the construction industry for decades.
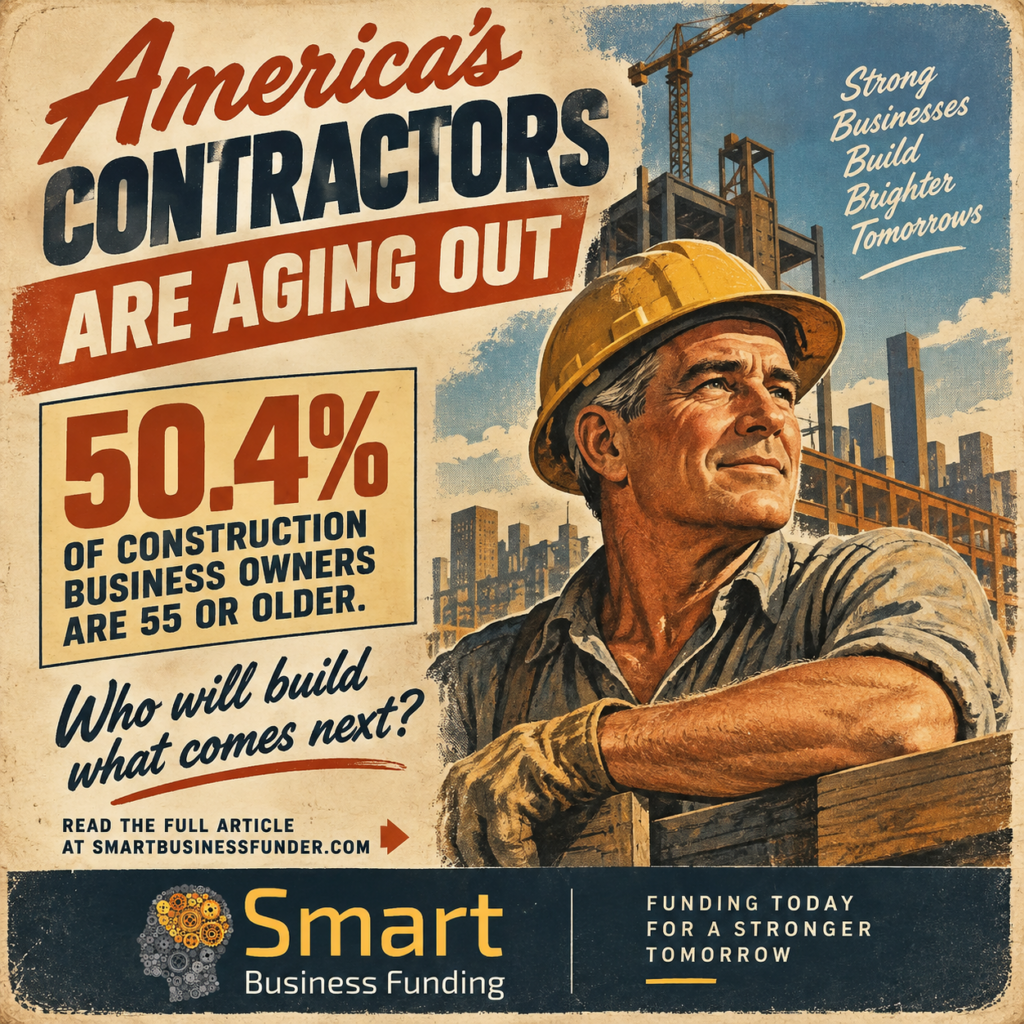
More than half of construction business owners are age 55 or older.
According to U.S. Census Bureau Annual Business Survey data compiled in CPWR’s Construction Chart Book, 18.9% of construction business owners are age 65 or older and another 31.5% are between 55 and 64.
Combined, that means 50.4% of construction business owners are at least 55 years old.
The numbers raise a question that goes far beyond retirement:
Who will own, operate, and grow America’s construction companies when today’s generation of contractors steps away?
For thousands of established construction businesses, succession may become one of the defining challenges—and opportunities—of the next decade.
More Than Half of Construction Business Owners Are 55 or Older
Construction has an unusually mature ownership base.
The Census Bureau data compiled by CPWR breaks down construction business owners by age as follows:
- 18.9% are 65 or older
- 31.5% are ages 55–64
- 25.2% are ages 45–54
- 24.4% are under age 45
Put another way, approximately three out of every four construction business owners are at least 45 years old, while only about one-quarter are younger than 45.
That doesn’t mean half of America’s contractors are about to retire.
A 55-year-old business owner may continue operating a company for another 10, 20, or even 30 years. Many contractors also remain deeply involved in their businesses long after the traditional retirement age.
But demographics eventually become economics.
Every established construction company ultimately needs an answer to the same question:
What happens when the owner no longer wants to run it?
For an industry built heavily around privately owned businesses, the answer matters.
A Construction Company Is More Than Its Equipment
When people think about the value of a construction company, they may picture trucks, excavators, tools, warehouses, or other physical assets.
But an established contractor can represent decades of accumulated business value.
That may include:
- Experienced employees and crews
- Customer and contractor relationships
- Supplier relationships
- Industry reputation
- Licenses and certifications
- Estimating and bidding expertise
- Project-management systems
- Equipment and vehicles
- Vendor terms
- Local market knowledge
- A history of completed projects
- Referral networks
- Specialized technical knowledge
Some of these assets are easy to see on a balance sheet.
Others are not.
Consider a contractor who has spent 30 years building relationships with developers, property managers, suppliers, subcontractors, architects, and customers.
The owner’s knowledge of the local market may be extremely difficult to replace.
When that person retires without a succession plan, America doesn’t simply lose an older business owner.
It risks losing some of the knowledge and relationships that helped make the business work.
The Contractor Retirement Challenge Is Also a Succession Challenge
Retirement does not necessarily mean closing a construction company.
An established contractor has several potential paths.
The business could be transferred to a son or daughter. A partner could acquire the owner’s interest. A senior employee or project manager could take over. Another construction company could make an acquisition. An outside entrepreneur could purchase the business.
But succession isn’t automatic.
A highly successful contractor can spend decades learning how to build a business without ever developing a plan for transferring it.
That creates an important distinction:
Building a valuable construction company and building a transferable construction company are not necessarily the same thing.
A business that depends almost entirely on its founder may be difficult for someone else to operate.
By contrast, a company with experienced management, documented processes, strong financial records, diversified customer relationships, and a capable workforce may be much easier to transition.
For construction business owners approaching retirement, succession planning can therefore become part of protecting what they spent decades building.
The Next Generation of Contractors May Buy Businesses Instead of Starting Them
The aging of construction ownership doesn’t have to be viewed exclusively as a crisis.
It may also represent an extraordinary entrepreneurial opportunity.
For generations, the traditional path to becoming a contractor has often looked something like this:
Learn a trade. Gain experience. Develop relationships. Start a small company. Win customers. Hire employees. Buy equipment. Build a reputation. Grow slowly over many years.
That path will continue.
But another path could become increasingly important:
Buy an established construction business from an owner who is ready to retire.
For the right buyer, acquiring an existing company can potentially provide something that starting from scratch cannot: an operating platform.
Depending on the business, that might include employees, equipment, existing customers, contracts, systems, revenue, and an established reputation.
The buyer still has to operate the company successfully.
But instead of beginning at zero, the next generation of construction entrepreneurs may have an opportunity to build upon companies created by the generation before them.
From Foreman to Construction Business Owner
Some of the most logical future owners may already be working inside construction companies today.
Consider an experienced foreman, superintendent, estimator, project manager, electrician, plumber, HVAC technician, or other skilled professional.
That person may already understand the company’s customers, employees, projects, and day-to-day operations.
What they may not have is ownership.
As older construction entrepreneurs begin thinking about succession, employee and management transitions could create a bridge between generations.
A veteran contractor gets an opportunity to preserve the company.
A younger construction professional gets an opportunity to become an entrepreneur.
Employees may get continuity.
Customers may keep working with the same organization.
And decades of accumulated knowledge have a better chance of remaining inside the business.
For some construction companies, the future owner may already be walking onto the jobsite every morning.
Hispanic Entrepreneurs Are Already Reshaping Construction Ownership
Age isn’t the only demographic story changing the construction industry.
Ownership data also shows that Hispanic entrepreneurship has an especially significant presence in construction.
According to the Census Bureau data compiled by CPWR, 24.2% of construction businesses are Hispanic-owned, compared with 15.4% across all industries.
That gap is significant.
Construction has long provided pathways through which skilled workers can eventually become independent contractors and business owners.
As older owners eventually transition out of their companies, Hispanic entrepreneurs could play an increasingly important role in the industry’s next generation of ownership.
That transition may happen in several ways.
Some entrepreneurs will launch new companies.
Others may take over family businesses.
Some experienced employees may become owners.
Others may acquire established construction companies.
The result could be an industry that looks considerably different 10 or 20 years from now—not because demand for contractors disappears, but because ownership changes hands.
Construction Business Ownership Remains Overwhelmingly Male
Another demographic gap remains substantial.
Approximately 85.3% of construction businesses are male-owned, according to the Census Bureau data compiled by CPWR.
Across all industries, the comparable figure is 55.9%.
That makes construction ownership dramatically more male-dominated than business ownership overall.
The statistic also points toward another potential source of future entrepreneurs.
As women expand their participation across construction management, engineering, skilled trades, estimating, project management, and entrepreneurship, the industry’s ownership demographics may eventually begin to change as well.
The question isn’t simply who replaces retiring male contractors.
It is whether the next generation of construction ownership becomes broader than the generation before it.
Why Construction Business Succession Is Different
Transferring a construction company can be particularly complicated because construction businesses often have significant ongoing capital requirements.
A contractor may need to pay for:
- Materials
- Payroll
- Subcontractors
- Equipment
- Vehicles
- Fuel
- Insurance
- Deposits
- Permits
- Jobsite expenses
Those costs do not always align neatly with when customers pay.
A profitable contractor can therefore still experience periods of substantial working-capital pressure.
This becomes particularly important during an ownership transition.
Imagine acquiring an established contractor and immediately inheriting multiple active projects.
The business may be healthy, but payroll still has to be met. Materials still need to be purchased. Equipment may need repairs or replacement. New projects may require upfront spending.
The purchase of the business is only part of the capital equation.
The new owner also needs enough liquidity to operate and grow it.
The Construction Cash Flow Problem Doesn’t Disappear After an Acquisition
Construction companies can face an unusual financial reality.
A contractor may win a major project—which is good news—and simultaneously need significantly more cash.
Why?
Because growth costs money before it produces cash.
A larger project can require additional labor, materials, equipment, vehicles, insurance, or subcontractors.
The contractor may have to spend substantial amounts before receiving all of the corresponding project revenue.
That means a company’s biggest opportunity can also create one of its biggest short-term capital needs.
For a new owner, this can be particularly important.
Acquiring an established construction company without adequate working capital can leave the buyer owning a valuable business but struggling to fund its operations.
Successful succession therefore requires thinking beyond the acquisition price.
It requires thinking about what the company will need the day after the transaction closes.
Capital Could Help Determine Who Owns the Next Generation of Construction Companies
The coming ownership transition isn’t simply a demographic issue.
It is also a capital issue.
There may be experienced tradespeople who are capable of operating companies but lack the capital necessary to make the transition into ownership.
There may be existing contractors who see an opportunity to acquire a competitor but need additional working capital after the acquisition.
There may be family members taking over businesses who need to modernize equipment, hire employees, expand into new markets, or take on larger projects.
Access to business funding alone won’t solve the construction succession challenge.
But capital can influence which entrepreneurs are able to act when opportunities appear.
That is particularly important in an industry where timing matters.
A new contract, equipment opportunity, acquisition, material purchase, or expansion may require a business owner to move quickly.
What Construction Owners Can Do Before Retirement
For construction company owners who expect to retire eventually, succession planning doesn’t need to begin six months before leaving.
Starting earlier can create more options.
Build a Company That Can Operate Without You
If every important customer calls the owner personally and every major decision requires the founder’s approval, transferring the company may be difficult.
Developing managers and documented processes can make a business less dependent on one person.
Keep Financial Records Organized
Potential buyers, partners, lenders, and advisors need to understand the company’s financial performance.
Clean records can make the business easier to evaluate.
Develop the Next Generation of Leadership
The future owner or operator could already be an employee.
Giving talented managers greater responsibility can help reveal who has the ability to lead.
Understand What the Business Is Actually Worth
Revenue alone doesn’t determine business value.
Profitability, customer concentration, assets, liabilities, contracts, management, growth prospects, and owner dependence can all matter.
A qualified business valuation professional can help owners understand what they’ve built.
Don’t Wait Until You Have to Sell
Time creates options.
An owner who begins succession planning years in advance may have more flexibility than someone forced to make a quick decision because of health, family circumstances, or burnout.
What Future Construction Business Owners Should Consider
For younger contractors, skilled tradespeople, and entrepreneurs, the demographic shift creates a different set of questions.
Instead of asking only:
“How do I start a construction company?”
It may be worth asking:
“Is there an established construction company I could eventually take over?”
Prospective buyers should carefully evaluate factors including financial statements, customer concentration, project backlog, equipment, liabilities, employee retention, licensing requirements, reputation, contracts, working-capital needs, and the seller’s role in maintaining customer relationships.
Buying a business is not automatically safer than starting one.
An existing company’s problems can transfer along with its assets.
Proper legal, financial, tax, and operational due diligence is essential.
But for the right entrepreneur and the right business, acquisition can provide a path into construction ownership that previous generations had less opportunity to pursue.
What Happens If Nobody Takes Over?
This may ultimately be the most important question.
Suppose an experienced contractor reaches retirement age and has no family successor, employee buyer, or outside purchaser.
The company may eventually close.
Competitors might absorb some customers and employees.
But some of the business’s institutional knowledge can disappear.
Multiply that scenario across roofing, electrical, plumbing, HVAC, concrete, masonry, welding, excavation, paving, and general contracting companies around the country.
The issue becomes bigger than individual retirement decisions.
It becomes an industry transition.
America doesn’t merely need enough construction workers.
It needs the next generation of construction business owners.
Who Will Build What Comes Next?
The aging of America’s construction business owners shouldn’t be interpreted as the decline of American construction.
It could instead mark the beginning of one of the industry’s most significant ownership transitions.
Today’s established contractors have spent decades building companies, training workers, serving customers, purchasing equipment, creating relationships, and developing expertise.
The next challenge is transferring that value.
Some businesses will pass from parents to children.
Some will be acquired by competitors.
Some will be purchased by outside entrepreneurs.
Some employees will become owners.
New Hispanic entrepreneurs may continue expanding their already significant presence in construction ownership.
More women may enter an industry where ownership remains overwhelmingly male.
And entirely new construction companies will continue to be created.
The companies may survive even when their founders retire.
But that requires planning, capable successors, and—in many cases—capital.
The central question facing the industry is therefore not whether America’s older contractors will eventually step away.
They will.
The bigger question is:
Who gets the opportunity to build what comes next?
Business Funding for Construction Companies
Smart Business Funding works with established construction companies and contractors seeking capital for growth, working capital, equipment, payroll, materials, expansion, and time-sensitive business opportunities.
Businesses may qualify for up to $5 million per transaction, with a streamlined process designed for business owners who need to move quickly.
Smart Business Funding also works with industries and situations that may be difficult to fund through traditional sources.
Explore construction business funding with Smart Business Funding and see what options may be available for your business.
Funding is subject to approval and applicable terms. Business owners should consult appropriate legal, tax, financial, and business advisors when considering a business acquisition or succession transaction.
Sources and Methodology
This article relies on owner-demographic data from the U.S. Census Bureau Annual Business Survey, as compiled and presented by CPWR – The Center for Construction Research and Training in the Construction Chart Book.
The age statistics discussed in this article describe the distribution of construction business owners within the cited dataset. Demographic trends should not be interpreted to mean that an individual owner intends to retire at a particular age.
Industry trends and demographic statistics provide context about construction business ownership as a whole and do not predict the circumstances of any individual business.