Why Your Agency Is Broke on Paper and Rich on Invoices
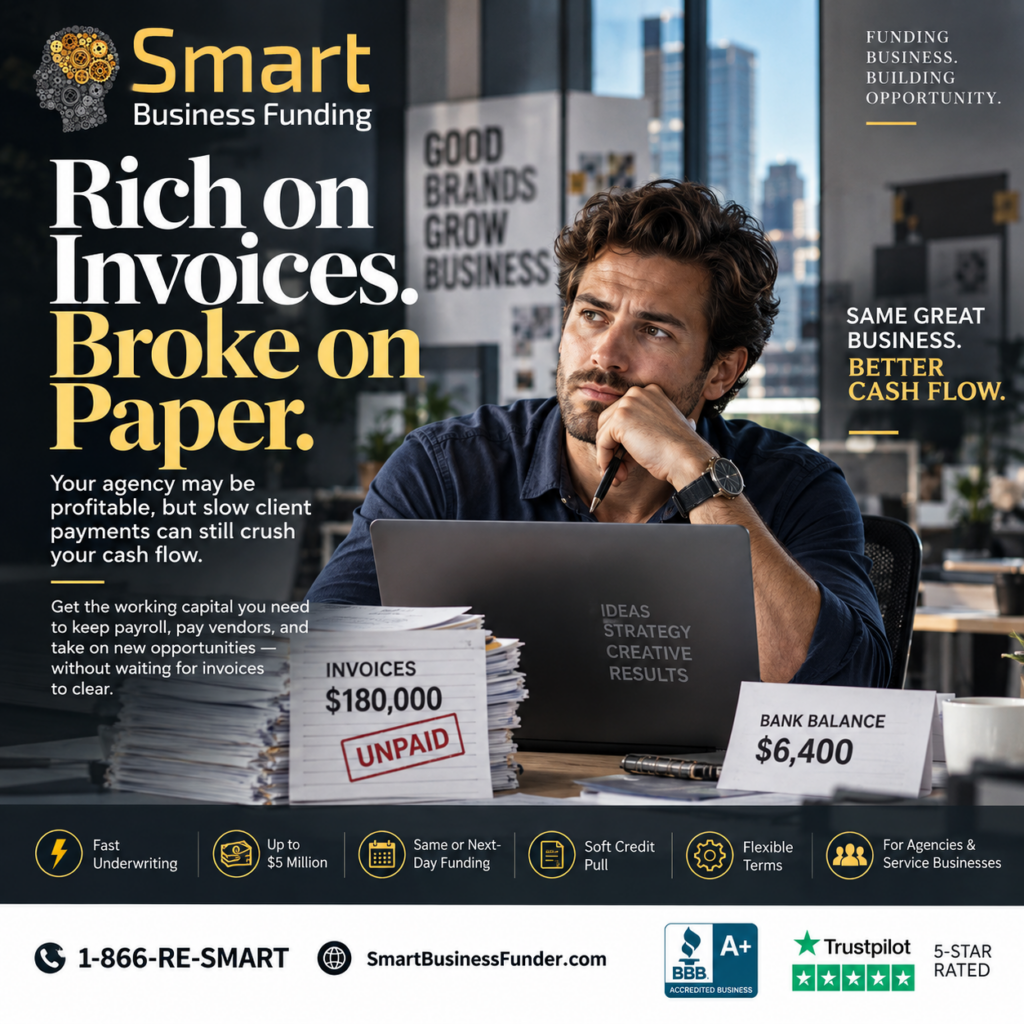
Your accounts receivable dashboard says $180,000. Your bank account says $6,400.
Payroll runs Friday.
If that gap sounds familiar, you’re not mismanaging your agency. You’re running a business that gets paid on a 30-, 45-, or 60-day delay for work your team already finished — while payroll, contractors, and software bills all run on a much shorter clock. That mismatch is the actual problem. It’s not a revenue problem. It’s a timing problem, and it deserves to be treated as one.
The Numbers Nobody Puts on a Slide
Here’s the version of this that agency owners talk about quietly, at conferences, after the second drink — not in the client-facing “here’s our growth story” deck.
Say your agency closes a $150,000 project for a client on standard net-45 terms. That’s not aggressive; it’s the default in this industry. The invoice goes out the day the work is delivered. The clock starts.
Meanwhile:
- Payroll runs weekly or biweekly, no matter what the invoice says.
- Contractors and freelancers expect payment on delivery or within days, not 45.
- Media buys, if you’re a marketing agency, may already be fronted out of your own account before the client has paid a cent.
- Software subscriptions, office lease, and overhead don’t pause for anyone’s payment terms.
So for 45 days, that $150,000 sits as an asset on paper — a number that makes the balance sheet look healthy — while your actual operating cash has to come from somewhere else. If you don’t have six weeks of payroll sitting in reserve (and most project-based businesses don’t, because reserve cash is exactly what gets used up fronting the last project), you’re stuck making decisions no one should have to make in a business that’s actually doing fine: delaying a contractor payment, drawing down a personal line, or turning down the next project because you can’t front the costs to start it.
That’s the trap. Not bad revenue. Bad timing.
Recognize this pattern? Check your eligibility now →
Why This Isn’t a “Struggling Business” Problem
There’s a stigma baked into how funding gets talked about — like needing outside capital means something’s wrong. For project-based, client-billed businesses, that framing doesn’t hold up.
Agencies, IT consultancies and other professional services firms, and production companies don’t run on a steady paycheck schedule. They run on invoices, fronted spend, and project cycles that swing between a big month and a slow one. That’s not dysfunction — it’s the structure of the industry, and it shows up across most of the industries this kind of financing serves, not just agencies. A healthy agency with strong client relationships and a full pipeline can still hit a wall the same week a $150K invoice is 20 days from clearing and payroll is due Friday.
The businesses that get into real trouble aren’t the ones that use funding to bridge that gap. They’re the ones that don’t — the ones that quietly turn down growth and expansion opportunities, delay hiring, or burn out an owner personally covering the float month after month.
What the Gap Actually Costs You
Run the math on net-45 terms against weekly payroll and the real cost of the gap becomes obvious:
- 6+ payroll cycles can pass between the day you invoice and the day a net-45 client pays.
- Every one of those cycles still has to be funded from somewhere — cash reserves, a personal card, or a founder’s personal savings.
- The bigger the project, the bigger the gap. A $150,000 invoice on net-45 terms isn’t a rounding error to smooth over; it’s often the majority of a small agency’s monthly operating cash, parked and unusable for six-plus weeks.
None of that shows up on a P&L. It shows up in a bank account, in real time, at the worst possible moment — usually right when you’d otherwise be saying yes to the next project. This kind of squeeze is exactly what’s covered in why cash-flow gaps call for emergency funding in the first place — the trigger usually isn’t a bad quarter, it’s a timing collision like this one.
Closing the Gap: Funding Sized to How You Actually Get Paid
This is the specific problem the Direct Fund Program is built around for media, marketing, and technology businesses: not a fix for a business that isn’t working, but a bridge for a business whose cash timing doesn’t match its billing terms. For the full mechanics of how funds move from application to bank account, see how it works.
The mechanics are straightforward:
- Funding amount: $10,000 to $5 million, sized to monthly revenue
- Time to funds: Same business day or the next business day once approved
- Underwriting: 1 to 5 hours in most cases, based on the business’s revenue and cash flow — not on pledging equipment or receivables as collateral
- Repayment: A fixed daily or weekly amount, known in advance, so there’s no guesswork layered on top of an already unpredictable invoice schedule
- Credit requirements: Scores around 500 and up typically considered, checked with a soft pull that doesn’t affect your credit score
Qualifying generally means the business itself is established and healthy — at least 1 year in operation with $50,000 or more in monthly revenue. That’s deliberate. This isn’t early-stage venture capital or equity investment; it’s revenue-based financing for agencies, IT firms, and production companies that are already generating real client revenue and just need that revenue to arrive faster than net-45 allows.
It’s also worth knowing this isn’t the only tool that fits this kind of gap. If the cash you need is tied to starting one specific new contract rather than an invoice you’ve already sent, purchase order funding may be the closer fit. And if the net-30/45/60 squeeze is a recurring pattern rather than a one-time crunch, a line of credit can give you standing access to draw on instead of reapplying every time a big invoice goes out. A funding specialist can help match the structure to how your agency actually gets paid — call 1-866-RE-SMART to talk it through.
Client Payment Terms vs. Funding Speed
Put the two timelines side by side and the gap this is solving becomes obvious:
| Payment Structure | Time to Cash |
|---|---|
| Direct Fund Program | Same / next business day |
| Net-30 client terms | 30 days |
| Net-45 client terms | 45 days |
| Net-60 client terms | 60 days |
Payment terms are standard industry ranges and vary by client and contract. Funding timeline reflects the Direct Fund Program’s typical underwriting and disbursement speed.
That’s the entire case in one table: your invoice is worth exactly what your client says it’s worth, whenever they get around to paying it. Funding just moves the “when” closer to the day you actually did the work.
What This Looks Like in Practice
Illustrative Composite Scenario
A software consultancy wrapped a major client engagement and invoiced on standard net-45 terms. The developers who did the work needed to be paid well before that invoice would clear. Tech services funding covered payroll on schedule and was repaid once the invoice came in — no disruption to the team, no personal cash drawn down to cover the gap.
This is a composite example built from patterns commonly seen across media, marketing, and technology businesses. It is not a record of a specific client, and every business’s outcome depends on its own financials. A few more scenarios like this — covering ad spend, production crews, and payroll specifically — are broken down on the media, marketing & technology funding page.
The Real Fix Is Matching Cash to How You Get Paid
You’re not broke. You’re owed money, on a schedule you didn’t set, by clients who negotiated those terms because it works in their favor, not yours. Six figures in receivables and an empty operating account isn’t a sign your agency is in trouble — it’s a sign your funding timeline hasn’t caught up to your billing terms yet.
If a $150,000 invoice sitting on net-45 has ever meant a stressful week of moving money around to make payroll, that’s exactly the gap this is built to close.
Check your eligibility now → or call 1-866-RE-SMART to talk through your specific invoice timing with a funding specialist — checking doesn’t affect your credit score. Prefer to ask questions first? Contact us or read more about Smart Business Funding.
Frequently Asked Questions
Why does my agency feel broke even with strong revenue on the books? Because revenue on an invoice and cash in a bank account aren’t the same thing. Net-30, 45, and 60-day terms mean the money is real but not yet accessible, while payroll and overhead run on a much faster clock.
Is it normal for agencies to front costs before getting paid? Yes. Fronting media buys ahead of client reimbursement, or paying contractors and crew before an invoice clears, is a common cash-flow pattern across agencies, IT firms, and production companies — not a sign of financial trouble.
How fast can funding actually close the gap? Through the Direct Fund Program, underwriting typically takes 1 to 5 hours, with funds generally available the same or next business day once approved.
Do I need strong personal credit to qualify? Not necessarily. Approval is based primarily on the business’s revenue and cash flow rather than personal credit history. Credit scores around 500 and up are typically considered, and eligibility checks use a soft credit pull that doesn’t affect your credit score.
How much can a media, marketing, or technology business get funded for? Funding ranges from $10,000 to $5 million, sized to monthly revenue. Businesses generally need at least $50,000 in monthly revenue and one year in operation to be considered.
What if this gap is a one-time thing, not a recurring pattern? It depends on what’s driving it. A single new contract that needs upfront capital is often a better fit for purchase order funding, while a recurring net-30/45/60 squeeze across multiple clients is closer to what the Direct Fund Program and lines of credit are built for. More scenarios are covered in the full FAQ library.